
As the demand for critical minerals and metals heats up, the discovery of significant new mineral deposits dwindles, and the cost of developing and running mining operations continues to rise, mining companies (and others) are increasingly looking to alternative resources and technologies in a bid to bring new supplies online.
Take lithium, for example, an element that’s a crucial component in many renewable energy technologies, including electric vehicle batteries. Projections show the lithium industry growing from US$22.2 billion in 2023 to nearly US$90 billion by 2030, by which time demand is expected to outstrip supply by around 1.42 million metric tonnes.
To keep pace with demand, refined lithium production would need to increase 86.5% over and above current projections—something which is inconceivable through current production methods and investment levels.
And it’s not just lithium that’s a problem. A recent report from the International Energy Agency, found that there’s likely to be a significant gap between prospective supply and demand for copper and other metals too. Anticipated mine supply from announced projects meets only 70% of copper demand and 50% of lithium demand, while balances for nickel and cobalt look tight relative to confirmed projects.
The issue is not a fundamental lack of resources—the Energy Transitions Commission states that “geological resources [for raw materials] exceed the total projected cumulative demand from 2022-50 for all key materials, whether arising from the energy transition or other sectors,”—it’s the current methods and models used to extract them. These simply cannot keep pace with demand in a way that’s economic, environmentally, and socially feasible.
The world needs to expand its idea of what constitutes as a ‘resource’, and it needs to do so quickly.
Brines: The ‘shale’ of lithium
Again, a good example of this shift in thinking can be seen in the lithium market.
Much like the shale extraction boom did for oil production in the early 2000s, mineral-rich brines are expected to significantly increase the global supply of lithium in the coming decades, supported by a technique called direct lithium extraction (DLE).
Around 54% of global lithium supply currently comes from the evaporation of brines with the balance from hard-rock mining operations. If successfully commercialised, analysts at Bloomberg expect the supply of lithium from evaporation and DLE technology to be comparable by 2030, at around 526,000t per year (see figure 1 below).

A 2023 study from Market Reports World valued the global DLE technology services market at US$54 million in 2022. This is expected to increase to US$782.2 million by 2029, with a compound annual growth rate (CAGR) of 46.6% during this period.
The potential for DLE to unlock future supply and economic growth is clearly significant. But what exactly is DLE? How does it work? And are there similar emerging technologies that could help us tap into sources of other critical metals?
Greg Gillian, vice president of Mining, Minerals and Metals, and Kevin Kammerzell, vice president of Mining, Minerals and Metals, at Stantec joined me to unpack this topic.
“Let’s go back to basics,” said Kammerzell. “The world has been mining lithium for quite some time, but much of that supply centres on extracting a mineral called spodumene from hard-rock excavations. That rock is crushed and processed to produce lithium concentrate.
“In the last 10 or so years, brines in deep aquifers, especially around salar (salt flat) regions of Chile and Argentina, have been increasingly leveraged for their concentrations of lithium. Companies have been working to bring that brine to the surface, place it in evaporation ponds and then let that brine evaporate to a suitable concentration for further use.”
There are environmental and social issues associated with the evaporation process, as well as economic challenges. First, evaporation ponds require a lot of land which can bring production into contention with other land uses.
Second, the evaporated water is lost to the atmosphere. Given that most of the world’s lithium production takes place in arid environments where communities don’t have enough freshwater to meet their needs, this seems to be an inefficient use of water resources.
Third, the process is slow. It requires an average of 12-18 months to produce suitable concentrates via evaporation, and recovery rates are relatively low at 40-60%.
In contrast, DLE has the potential to produce recoveries in the 70-90%+ range in just a few days. Land requirements are reduced by greater than 20 times, and water usage is less, especially if the brines are reinjected into the aquifer post extraction.
According to Goldman Sachs, “these benefits may support improved timelines for community and permitting approval, while enhanced production on higher recoveries could also improve/bring forward government take from projects”.
Cost wise, the capital intensity range of DLE is comparable with traditional pond projects after adjusting for higher recoveries, and operating expenditure (OPEX) is lower. DLE projects have an average OPEX of ~US$2,800-3,600/t of lithium carbonate equivalent (LCE) compared with a traditional pond range of ~US$3,300-4,900/t LCE.
How does DLE work?
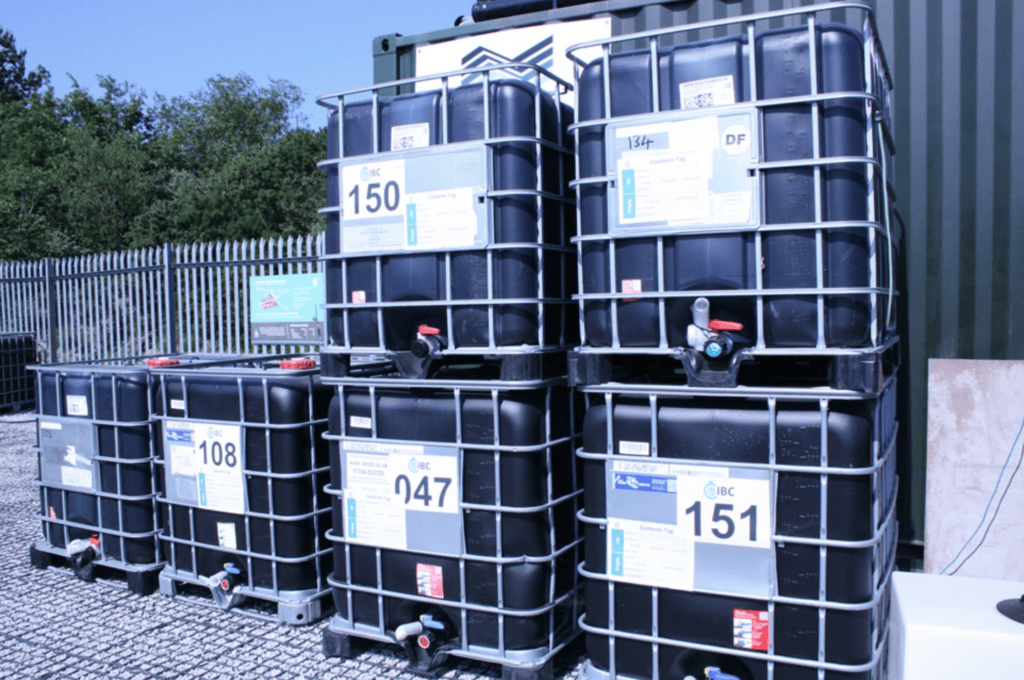
In a DLE operation, brine is pumped from an underground reservoir or aquifer to a processing unit where technologies that utilise filters, membranes and/or ceramic beads are used to precipitate only the lithium from the brine.
The spent brine can then be reinjected into the aquifer or, depending upon the technologies used to treat the brine, freshwater could be generated as a byproduct. Kammerzell pointed out that this could potentially be used to create a commercial opportunity or to engage local communities.
Many of the technologies used to facilitate DLE are commonplace in industries like wastewater treatment today.
“The technologies involved in DLE aren’t necessarily new,” said Kammerzell. “But the way in which they’re being applied to extract lithium is relatively new. Some, like reverse osmosis and ion exchange, have been around for decades. They’re used in purifying drinking water and in treating industrial waste waters.
“Others, like sorbent technologies, are specifically used to target the removal of specific elements in brines (i.e. lithium) and are therefore more consistent with traditional mining applications.”

According to Stantec’s research, there are more than 27 companies globally that are working towards or have already commercialised DLE methods. 17 of those are actively pursuing or have obtained patents for processes relating to lithium extraction. The most common technologies used in these processes are absorption, reverse osmosis, ion exchange, and chemical or electro-filter extraction.
“Not all orebodies are the same,” Kammerzell explained. “One technology might work well in a certain geography or brine, but it might not be applicable to others. As in a traditional mining project, companies will run bench tests on different technologies to see which will yield the highest metal recoveries for their resource at the lowest economical expense and impact to the environment.
“The most successful will advance to pilot-scale testing to check the purity of the concentrate, and then a demonstration plant which generates a saleable product in small quantities that can be distributed to battery manufacturers. Once contracts or offtake agreements are in place, then commercial scale development of the operation can begin.”
The need for speed in innovation
Gillian pointed out that while there are a number of companies with patented or patent-pending processes, many are still at an early stage in terms of the technology readiness level (TRL) – see figure 2.
At the time of writing (May 2024), two companies—Sunresin and Livent—had processes at TRL level 9. These are operating at a commercial scale on sites in Argentina and China. And there were several companies with technologies at TRL 7-8 (applicable at an existing operation for a given application), including Energy Source Minerals, Lilac Solutions and Veolia.
Even a few mining companies, including Rio Tinto (through Borax Inc), have patents pending on processes that will allow the extraction of lithium and other minerals, such as boron, from brines which was developed through Rio Tinto’s own internal research and development efforts.
The mining industry isn’t known for speed in the development and adoption of new technologies, but I asked Gillian: “Given the imperative surrounding critical mineral and metals supplies, would you say that DLE is progressing faster than most?”
“Yes,” said Gillian. “Traditional mining projects, including those with lithium resources, require somewhere between 7-17 years to reach commercial production due to the large-scale footprint. For comparison, the DLE process occupies a much smaller area than an openpit mine extracting spodumene or a large evaporation pond system supporting brine concentration.
“With limited impact, this may translate to faster permitting and startup. But considering the increase in production that’s required to meet global sustainability targets, some radical thinking is necessary.
“We’re talking about lithium, but there are other metals that can be extracted from brines or solutions using a different combination of technologies. So, the implications of the technology are potentially much larger.”
Kammerzell explained: “For instance, there’s an extra process step that can be included which involves injecting an acid into the aquifer to allow the leaching of copper in-situ. The solution would then be pumped out of the aquifer and the copper extracted using a process, such as solvent-extraction/electro-winning (SX/EW).
“In the US, in the Smackover formation in Arkansas, there are operations that have been extracting bromine from brines for more than 30 years by infusing the brine with chlorine and steam.”
Gillian said: “If we really wanted to be adventurous, then there are critical minerals in seawater. But the concentrations are so low that they wouldn’t be attractive to recover at this point.”
“It’s an interesting possibility though, especially given that some mining companies with operations in arid places like Chile are using desalination to obtain freshwater,” I said. “I wonder if there might be the potential for byproducts?”
“Maybe, in time, if companies can figure out how to produce a concentrate that’s saleable,” said Kammerzell. “That brings the concept of a circular economy into the conversation too. If we look at markets like potash, are there lithium concentrations in potash formations or tailings that are worth going after?”
Gillian added: “Lithium recovery rates from traditional brine ponds are comparatively low and, in the future, it is probably worth looking at pond residues to see if valuable minerals could be recovered using alternative processing methods.
“Waste valorisation presents a huge opportunity for both existing and future operations to meet critical metal demands and minimise their environmental impacts.”
Tapping into alternative resources
Today, there are a number of geothermal and petrochemical operations across the globe that exploit brines and are looking to produce critical metals/minerals as a byproduct.
For example, Vulcan Energy Resources, through its Zero Carbon Lithium project, is adapting commercially proven technologies to produce battery-quality lithium from naturally heated subsurface brines in Germany’s Upper Rhine Valley.
In the UK, Cornish Lithium is also looking at the potential for deep geothermal waters extracted at its United Downs project to produce heat as well as net zero lithium.
And the potential doesn’t stop at brines… Some companies have been ‘mining’ industrial waste for critical minerals for years. Copper has the most critical mineral byproducts of any metal; around 90% of the world’s tellurium, which is used in thin film photovoltaic solar panels, is contained in copper ore.
Realising this, Rio Tinto began producing tellurium from waste at its Kennecott Copper refinery in Utah, US, in 2022. The company is now one of only two US producers of tellurium.
Tailings reprocessing is another example of how innovative technologies can potentially bolster critical metals and minerals supplies. For example, in Sweden, LKAB’s ReeMAP project will extract rare earth elements and other minerals from tailings produced at its Kiruna and Gällivare/Malmberget mines.
“When it comes to critical metals, we need to consider technologies that have been developed in other industries and apply traditional equipment in innovative ways if we want to avoid supply shortages,” said Gillian. “When we start to think outside of the box, there are lots of alternative resources.
“The issue right now is that battery metal prices are lower than two or three years ago, and companies are struggling to access the capital needed to develop these projects.”

Kammerzell added: “From a supply chain security perspective, using alternative deposits could present an opportunity for some economies to become less dependent on FEOC countries for supplies of critical metals.
“Further advancing technology will limit the environmental footprint mining activities normally require and improve extraction qualities. This creates a win-win scenario for nearby communities and beneficial use for downstream consumers to a lower-cost, abundant supply of these critical minerals.
“From a circular economy perspective, it makes sense to get the most out of every molecule, to create new product streams, to produce less waste, and to recycle material wherever possible. Mining companies need to make sure they’re doing everything they can to limit their impact while providing resources. Critical minerals and metals can provide a driver for that.”
This article is sponsored by Stantec